Saturday, January 10, 2009

Will Aging Boomers Change Housing?

Will Aging Boomers Change Housing?

Housing for boomers will be a growth industry in the next 20 years, says Matt Thornhill, co-author of the book "Boomer Consumer: Ten New Rules for Marketing to America's Largest, Wealthiest and Most Influential Group."

Thornhill predicts the following within the next couple of decades:
  • Boomers will renovate their existing homes to make them more comfortable and safer as they age.
I've moved 650+ miles so I can be near the kids.
  • Boomers will turn neighborhoods that have good access to shopping and other services into retirement areas with co-housing and other kinds of intergenerational living.
Do not think so, I might go live near the beach and the kids perhaps - but I would not want to live in a co-housing.
  • Pods — one-bedroom structures wired and plumbed to the main house — will be a popular answer for families with older members.
May be if that the older members are your own parents and not your in-laws.
My mother-in-law lived with us for 8 years. It was the best arrangement for her during the last
8 years of her life. IT WAS THE BIGGEST SACRIFICE FOR OUR FAMILY and believe me
it would be FOR ANYONE' LIFE.

  • Boomers will prefer city to suburban living.
NO Way, I lived in the city most of my life, I love the country now or the beach definitely NOT THE CITY!!!
  • Fewer new structures will be built with services for older adults housed in schools and churches.
Source: Seattle Post-Intelligencer, Rita Robinson (12/16/08)

http://www.realtor.org

Thursday, October 23, 2008

What Retirement Plan Should You Offer?

What Retirement Plan Should You Offer?

Click Here


Boomers Make The Fear Worse
Rich Karlgaard explains why the 2008 collapse is causing more panic than previous downturns.
2008-10-21

http://www.forbes.com/video/?video=fvn/talkback/rk_vlog102108


Boomers Make The Fear Worse
Rich Karlgaard explains why the 2008 collapse is causing more panic than previous downturns.
2008-10-21

http://www.forbes.com/video/?video=fvn/talkback/rk_vlog102108

Retirement Index

Sun Life Financial Unveils UnretirementSM Index to Determine Future of Retirement

Initial Study Shows Only Half of Americans Plan to Retire at 67;

Staying Mentally Engaged Tops Extensive List of Drivers to Stay in the Workplace

WELLESLEY, MA (Oct. 1, 2008) - The U.S. division of Sun Life Financial Inc. (NYSE:SLF, TSX:SLF) today announced the Sun Life Financial UnretirementSM Index, a first-of-its-kind measure to track the changing attitudes and expectations American workers have regarding retirement. The Index, to be released multiple times each year, will gauge how economic, financial and societal forces are affecting working Americans, and will forecast their future retirement decisions that will impact individuals, the government, employers, and the broader economy.

Sun Life’s research uncovers surprising results as the median age of Americans rises and more Baby Boomers prepare for important decisions, like when to take Social Security and when to exit the workplace. Almost half (48%) of the American workforce believes it will still be working at the traditional retirement age of 67, and four of the five top reasons given were not financial in nature. Instead, the most cited reason for continuing to work (83%) was “to stay mentally engaged” – a finding consistent across all income levels, gender and age demographics.

“As our workforce evolves and attitudes are impacted by economic conditions and world events, the nature of retirement in America evolves as well,” said Bob Salipante, President, Sun Life Financial U.S. “Traditional views on retirement are quickly evolving and more Americans are choosing to be unretired. This Index for the first time shows how changes in the economy, politics, healthcare and lifestyle are all critical factors in more and more Americans choosing to continue working during traditional retirement years.”

Unretirement is defined as working at least 20 hours per week after the age when one is eligible to receive full Social Security benefits. Supporting data also show that a significant portion of those with the means to retire are instead deciding to stay in the workforce. Nearly 40 percent of workers surveyed with household assets of more than $500K still plan to work at least part-time, while overall, more than 77 percent of those planning to work beyond age 67 will do so to earn enough money to live well. Finances, however, are not the only driver to continue working past age 67. The study revealed that 83% plan to be working at 67 “to stay mentally engaged.”

"The Index findings reveal differing expectations between the generations. At the intersection of generational values and external influences, the attitudes of both older and younger generations regarding work and active lifestyles are evolving," said noted author and expert Dr. Carol Orsborn, Ph.D. "In particular, the Boomer generation is approaching the traditional age of retirement with their lifelong habit of challenging societal norms intact. They stand at the portal of advancing age more driven by their desire to stay engaged with achievements and family relationships than by the value of their portfolio."

The Sun Life Financial Unretirement Index also examined a broad array of factors including economics, healthcare, personal finance, and government benefits and their potential impact on Americans’ plans for retirement. Survey findings show dramatically different levels of optimism about when generational groups plan to retire and what they expect to rely upon in retirement.

Sun Life also found that only 46 percent of those surveyed are “very confident” that they will have enough money to take care of basic living expenses at the traditional retirement age of 67. Only 28 percent are “very confident” that they will be able to take care of medical expenses and 26 percent are “not at all confident” that they will be able to do so.

“Sun Life's Unretirement Index shows that retirement at an early age may soon be a thing of the past,” said Laurence Kotlikoff, Professor of Economics at Boston University. “According to the Index, half of today's workers plan to work beyond age 67 – a dramatic reversal of the postwar trend toward early retirement. These plans to delay retirement reflect a desire to stay mentally engaged, but also real anxiety about financing retirement. Workers are very worried about their ability to rely on two historic mainstays of retirement – Social Security benefits and employer-provided benefits. Indeed, fewer than half of workers express strong confidence in being able to cover the basics in retirement, let alone live it up in retirement. The Index also shows that retirement confidence varies considerably from worker to worker depending on economic and demographic factors. Older workers seem more aware of and concerned by a retirement-financing gap, but neither young or old workers are eager to work harder or longer to close this gap. Instead, they express a willingness to cut spending, which may signal a change in future saving behavior.”

INDEX FINDINGS

At age 67, Americans can receive full Social Security benefits. While availability of government benefits has traditionally driven many Americans’ retirement decisions when to retire, the Unretirement Index shows this traditional view on retirement is evolving. Additional Index findings follow.

When do Americans plan to retire?

Almost half (48%) of America’s workers plan to work past the age of 67.

· Younger generations are more often planning to retire at age 67 than their older counterparts. Fifty-eight percent of workers age 30-39 believe they will be retired at 67 compared to only 45 percent of those aged 60 and over.

· Nearly one in three Americans plans to work at least part-time past the age of 67.

Why are Americans working later in life?

Four out of the five reasons cited for continuing to work past age 67 are not financial.

· The number one reason (83%) people don’t plan to retire at age 67 is to stay mentally engaged.

· Among those with total net assets of less than $100,000, 81 percent said they will continue to work to earn enough money to live well, virtually the same percentage that want to keep working to stay mentally engaged.

· Among those with total net assets of between $100,000 and $500,000, 72 percent will continue to work because they love their careers and 66 percent said they were not ready to end their careers.

What are the factors influencing retirement?

Americans have less confidence in factors influencing their retirement over which they have less control.

· Americans have lower confidence in the economy than any other factor measured by the Unretirement Index.

· The younger generations have little confidence that government benefit programs like Social Security and Medicare will be available when they retire. Sixty three percent of workers age 30-39 don’t believe that Social Security will be available and also cite employer healthcare benefits as a reason to work past age 67.

· American workers are much more likely to cut back on spending and reduce debt to improve their retirement prospects rather than seek to increase their income or change their investment mix. Eighty-two percent would reduce spending while only 58 percent would alter their investments.

· Only 46 percent of all workers are very confident that they will have enough money to take care of basic living expenses when they reach traditional retirement age, and only 28 percent are very confident they will be able to take care of medical expenses.

· Despite believing federal drug benefits will not exist in coming years, only 59 percent of those surveyed cited healthcare costs as a reason they plan to continue working.

ABOUT THE SUN LIFE FINANCIAL UNRETIREMENT INDEX

The Sun Life Unretirement Index measures attitudes and expectations American workers have towards issues that influence retirement. The index ranges from 0 to 100, and this inaugural study yielded an overall index score of 46. The lower the index number, the more negative or

pessimistic people's outlook are on issues that influence retirement. The overall index is a composite score based on the performance of five issue-specific indices, including: the "economic index" (score = 30), the "personal finance index" (score = 48), the "health index" (score = 69), the "government benefits index" (score = 42), and the "employer

benefits" index (score = 43).

Methodology

The study was conducted between August 9 and 19 of 2008. Telephone interviews were conducted by Interviewing Service of America using a random-digit dial (RDD) sampling method. Quotas and weights were applied to gather a sample of 1,515 people working either full- or part-time, which was representative of the U.S. working population between the ages of 30 and 66. The sample was also representative in terms of gender and four-region census break. Analysis and construction of indexes involved the application of factor analysis. Final indexes are based on summated averages across the attributes which make up an index. For more information and detailed findings of the Sun Life Unretirement Index visit www.unretirementindex.com

Age groups were divided by workers in their 30s, 40s, 50s, and 60+ and by three ranges of total assets, not including the net worth of the person’s place of residence (less than $100K, between $100K and $500K, and greater than $500K). This sample has a margin of error of 2.5 percent at the 95 percent confidence interval.

About Sun Life Financial

Sun Life Financial is a leading international financial services organization providing a diverse range of protection and wealth accumulation products and services to individuals and corporate customers. Chartered in 1865, Sun Life Financial and its partners today have operations in key markets worldwide, including Canada, the United States, the United Kingdom, Ireland, Hong Kong, the Philippines, Japan, Indonesia, India, China and Bermuda. As of June 30, 2008, the Sun Life Financial group of companies had total assets under management of US $404.7 billion. Sun Life Financial Inc. trades on the Toronto (TSX), New York (NYSE) and Philippine (PSE) stock exchanges under ticker symbol SLF. Visit Sun Life Financial's website at www.sunlife-usa.com.

###


Chris Groppa

Account Supervisor

Fleishman-Hillard, Inc.

chris.groppa(@)fleishman.com

Delivering Results at the Point of Impact

Friday, September 19, 2008

Moving Can be a Taxing Decision

Moving Can be a Taxing Decision

By James O. Armstrong

So, what motivates employees to move during retirement? While there may be other factors, this list covers a number of the considerations many of our fellow baby boomers and others consider important in making such a decision.

First, we may decide to move because a specific job offer emerges from either the private or public sector. This offer to someone in greater demand could also include a future independent contractor status or registration with a speaker's bureau or talent agency, for example. Or, it may include starting your own business or even buying a franchise with an established business plan and strategy to pursue.

Second, we may decide to move because of family considerations, which range from aging parents to relocating so that we can be closer to our children and grandchildren. In fact, a number of my daughter's closest young adult friends in Greater St. Louis have talked about their parents taking precisely this step recently. By the way, this observation includes the movement of grandparents to the St. Louis area, who have never before lived in that region.

Third, men and women also choose to move to a more exciting part of the US or they may choose to live abroad, which an increasing number of Americans are now deciding to do. For example, a fellow baby boomer web entrepreneur, Ann Fry, decided to move from Austin, TX to New York City over the past year and she has never looked back on her decision. The 62 year old Ann runs a successful web site plus works as a motivational speaker and career coach. So, part of her relocation formula has included an upsurge in her speaking engagements and coaching assignments, especially since she moved to New York, despite the warnings of doom and lack of success from her Austin, Texas-based friends.

Fourth, other men and women choose to move to a different part of the US especially for tax reasons. But, of course, the question, which quickly emerges in this complex set of variables is "which taxes?" Many of us no doubt already know Texas or Florida (part-time) citizens, who have emigrated to these states because neither levies a state income tax. Of course, the winning formula is that "they" actually live in their adopted states for one-half of the year plus one day.

But, did you know that there are actually a total of seven states with no income tax as follows: (1) Alaska, (2) Florida, of course, (3) Nevada, (4) South Dakota, (5) Texas, (6) Washington and (7) Wyoming. In addition, New Hampshire and Tennessee only tax interest and dividends.

Likewise, it should be clearly said that a total of 26 states plus the District of Columbia do not tax Social Security benefits. IMPORTANT: Our web site, www.NowWhatJobs.net, is against any states taxing Social Security income. From our standpoint, because of the current and coming labor shortages and especially because of the current skills shortages, our society cannot afford to do anything, which has the net effect of discouraging men and women from continuing to work in America.

Finally, other men and women will factor some or all of these issues into consideration, when deciding where and when to move in our society. In the final analysis, even local sales taxes and property taxes can and should enter into this equation. For example, the City of Chicago recently passed an incredibly high local sales tax, which put this great city at or near the top of local sales taxes in the whole US among major cities. Of course, this consideration only becomes important when someone wants to buy something, whatever that may be.

To tax or not to tax -- that will indeed be the question for state and local governments in the future in the US and elsewhere, as a wave of baby boomers begin to consider all of their relocation factors and options. "Yes," state and local governments would like the bank deposits, which provide the necessary capital needed for consumer loans and local businesses to expand and create even more jobs in that area. "Yes," state and local governments would also like men and women, who will not be adding to the local student population in our nation's public schools, but who will never the less be adding to the local property tax base. "Yes," state and local governments would also like to have men and women, who are creditworthy and who have a greater equity position in their homes move into the community.

But, what if anything are these state and local governments willing to do in order to court "our" favor, you might logically ask? This writer submits to you that the answer to this question will cause state and local governments around the US to make a whole series of different decisions, both now and in the near future, in order to demonstrate "their friendliness" to my fellow baby boomers, who are 78 million strong just in the US.

JAMES O. ARMSTRONG BIOGRAPHY

James O. Armstrong, President of NowWhatJobs.net, Inc., http://www.nowwhatjobs.net, also serves as the Editor of NowWhatJobs.net. NowWhatJobs.net is the resource for job and career transitions for workers 40 years old and over, Baby Boomers and Active Seniors. Read NowWhatJobs.net for skills training, relocation options, job opportunities and much more. In addition, James is the author of "Now What? Discovering Your New Life and Career After 50" and the President of James Armstrong & Associates, Inc., a media representation firm based in Suburban Chicago.

Tuesday, August 12, 2008

Retirement Planning: 4 Tips to Help you Retire Worry Free

Retirement Planning: 4 Tips to Help you Retire Worry Free
By: Jim Gianoglio.

Retirement planning can be stressful. If you think about it, you are planning for a time in your life when you won’t be working, yet you’ll still be consuming. There are a lot of things to consider in addition to day-to-day expenses: extended health care, emergencies, planning a legacy… the list is long. How can you make sure you are saving enough for retirement?

Here are four ways you can plan for your retirement worry free:

1. Know yourself and prepare for change. Try out new roles in social, community, charitable, cultural, or recreational organizations and try new activities before you retire. Why? Because it’s important to know what you’ll be interested in so you have an idea of what kind of expenses you’ll face. In retirement you are going to have needs to fulfill and require new ways to keep stimulated. Now’s the time to figure out what your “drivers” are and what’s really important to you, if you haven’t already.

2. Increase savings. Having to increase your savings shouldn’t surprise you, especially if you hope to retire early. Put money aside whenever possible. One great way to save is to set up an automatic savings plan, or to boost your contributions if you already have one. Try and invest your income tax refund instead of spending it.

3. Plan for a longer retirement. Thanks to medical advances and healthier lifestyles, people are living longer. Sounds great, right? The only downside is you now have to plan for a longer retirement. Previously, you could expect to spend 15-20 years in retirement. Today, you should plan on creating a savings that will last for potentially 30 years.

4. Upsizing or downsizing. It is easy to say you don’t need to save as much because you won’t be as active and can downsize your lifestyle. In many cases, retirement is exactly the opposite. Extensive travel, fine dining, and joining an exclusive golf club are just a few of the upsizing many retirees embrace. While either choice is possible, they both require forward planning. The key to being successful with your planning is to be honest. Realistically decide if you want to live it up now that you have the time, and then tailor your financial plan to it.

Remember, retirement is your chance to do the things you’ve always wanted to do, but didn’t have time for. Using an online retirement planning calculator will get you started, but don’t stop there. A professional financial advisor can help you make your retirement an exciting new life by being financially prepared.


Retirement Planning Calculator

Tuesday, July 22, 2008

Condo Trends.

According to the article by M. Anthony Carr on Realty Times, the author said that Boomers are driving the trend of Less Is More.

He said that traditionally downsizing is not unusal for silver-haired generation. He added that in the 21st century, downsizing is speeding up since baby boomers are becoming enpty-nesters which tremendously changed their lifestyle.

"They are seriously considering the convenience of 'lock-and-go' versus a lifestyle tied to big homes," says Murray Lawson, to the Calgary Herald. The managing broker for Royal LePage Coast Capital Chatterton has been watching boomers seek out low-cost alternatives to the high rents and maintenance of the single-family dwelling lifestyle.

Carr stated that the downsizing of home mean that all the furnishings are going to have to be downsize as well. This trend got everyone involved inclding the Realtors as well as the furniture retail outlets. Condo buyers no longer can fit in king-sized bed for wall beds and smaller living room suits. No longer can they continued to have big comfy couch that looks perfect in the 240-foot living room in the traditional colonial. They are going to need a much small one in a 144-foot den in the luxury condo.

Moving consultant Jane Dewing in Calgary says it can actually be stressful, saying residents realize they "have to make conscious decisions to relinquish items they might have had for many years."

The article suggests that boomers downsize every 5 years and try to minimize the major downsizing at one time.

Read the whole article:

Tuesday, May 6, 2008

Theme Park For Boomers?


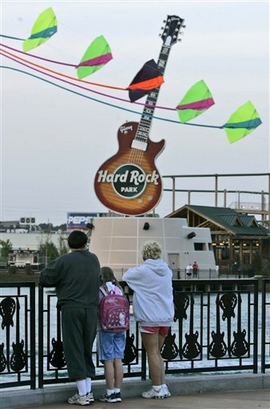
Visitors look out over the 55 acre Hard Rock park built around a lake dominated by 70 foot replica of a Les Paul guitar Saturday, April 26, 2008, in Myrtle Beach, S.C.

(AP Photo/Mary Ann Chastain)


Now that we are retiring, we can travel far and away.... I still wish that it was built in California though.

Led Zeppelin, Moody Blues rides at new Hard Rock Park in SC

By BRUCE SMITH, Associated Press Writer Tue May 6, 12:47 PM ET

MYRTLE BEACH, S.C. - The Led Zeppelin classic "Whole Lotta Love" throbs from the 1,200-watt sound system as the slick silver and white roller coaster nears the top of its serpentine track.

Lead singer Robert Plant shrieks, "Woman. You need. Loooooooove..." And as he does, riders scream as the car falls from a height of 155 feet, reaching speeds of 65 mph.

Welcome to Hard Rock Park, America's newest theme park and the first one built in the nation in a decade. Here the theme is not movies or fairy tales or water shows. It's that American invention, rock 'n' roll.

The $400 million park in the heart of South Carolina's $16 billion tourism industry had a soft opening in April that it called a "sound check." The grand opening is slated for June 2-3, with concerts by the Eagles and The Moody Blues.

As has Led Zeppelin, both groups have lent their names to key attractions at the 55-acre park built around a lake dominated by 70-foot replica of a Les Paul guitar.

The Eagles' "Life in the Fast Lane" roller coaster spins through what appears to be an abandoned saw mill as the hit song plays. "Nights in White Satin, The Trip" winds through the dark amid psychedelic lights and images set to the 1960s Moody Blue's hit.

Nearby looms a reproduction of the Statue of Liberty with sun glasses, and holding not a torch, but a Zippo cigarette lighter. Engraved on the pedestal is a quote from Neil Young: "Keep On Rockin' in the Free World." The park also hosts nightly fireworks shows choreographed to "Bohemian Rhapsody," and one of its eateries is called Alice's Restaurant, after the Arlo Guthrie song.

The park is the first foray by Hard Rock, best known for its cafes, into the amusement park business.

"We realized everybody had done movie parks," said Steven Goodwin, the park's chief executive officer. "Why do something everyone else has done in Orlando and Paramount parks around the country? We just thought rock 'n' roll was a natural."

Building a theme park around music guarantees an audience from children to seniors.

"Music is one of those things that connects emotionally with us," he said. "You hear a song and you immediately have a memory or a related emotional experience. That's what we're trying to create here."

"What younger kids have been exposed to is very eclectic because of the Internet and the iPod," said Jon Binkowski, the park's chief creative officer.

"Younger kids have been exposed to be the Beatles and the Rolling Stones and things like that."

The park is divided into areas such as British Invasion, which features the bus the Beatles used in the film "Magical Mystery Tour."

Among the other areas are Cool Country, Born in the USA and even Rock and Roll Heaven, where the names of 350 musicians playing in that big concert hall in the sky are engraved bricks and stone as a memorial.

Visitors can see swimmers and divers perform in a show called "Malibu Beach Party," play arcade games such as Whack-A-Boys-Band — similar to Whac-a-Mole — and catch live musical performances throughout the park.

All the while, rock music from different eras plays seamlessly through the park's elaborate sound system.

"You can layer rock 'n' roll over a theme park. It's just a natural," Binkowski said. "Music makes a connection that a movie doesn't. Movies continually have to tap back into music to get their flavor and their soul."

Hard Rock is the first new park built in the nation in a decade, according to the International Association of Amusement Parks and Attractions. There are about 400 amusement parks in the United States.

Hard Rock hopes to attract 30,000 visitors a day and about 3 million a year.

http://news.yahoo.com/s/ap_travel/20080506/ap_tr_ge/travel_brief_hard_rock_park;_ylt=AosJYLdpH8Lyp6mhHgcHBa2s0NUE